Jumio Industries

Fraud Prevention & Identity Verification for BNPL Lenders

Request More Info
Synthetic identities, bust-out schemes, and mid-repayment account takeovers all target the same gap: the months between approval and payoff. Jumio verifies real identities at checkout speed and keeps watching through the full repayment window.
Facial verification grid with three linked user profiles, representing identity matching across multiple accounts

Stop Fraud at Every Stage of the Buy Now Pay Later Lifecycle

Buy Now Pay Later (BNPL) lenders face a unique problem: approval decisions happen in seconds, but the window for fraud risk can stay open for months. Fraudsters exploit that gap, using synthetic identities and AI-generated documents to pass instant checkout approval, then disappearing after several purchases in classic bust-out schemes, or hijacking the account mid-repayment when it's least expected. Jumio verifies high risk real identities at speed and continues protecting the account through the full repayment window, so you can approve fast without approving fraud.

Primary Use Cases

Block Synthetic Identities and AI-Generated Documents at Checkout

Fraud rings increasingly use synthetic identities (a blend of real and fabricated personal data) paired with AI-generated or manipulated documents to pass instant Buy Now Pay Later approval. Because BNPL underwriting has to happen in seconds to preserve conversion, there's little room for manual review. Jumio ID Verification verifies document authenticity and Selfie Verification confirms a live, present applicant at speed, catching synthetic and AI-generated identity attempts before approval — without adding friction for legitimate customers.

Reverify the Account Holder Before High-Value Purchases

BNPL's extended repayment windows create an account takeover opportunity that doesn't exist in single-transaction lending, and a fraudster who compromises the account weeks or months after approval can make additional high-value purchases against an already-approved credit line. Jumio Authentication enables step-up reverification of the account holder before high-risk or high-value transactions during the repayment window, confirming the same person who was originally approved is the one transacting now.

Catch First-Party and Bust-Out Fraud After the Fact

Some of the hardest BNPL fraud to catch isn't visible at approval. With first-party or bust-out fraud, a borrower (or synthetic identity) builds a pattern of legitimate-looking purchases before deliberately maxing out and defaulting. This behavior often surfaces only after several transactions, once it's too late for checkout-stage controls to help. Jumio Watch continuously analyzes approved accounts for the behavioral and identity patterns associated with bust-out schemes, surfacing risk before it compounds into losses.

Catch Repeat Fraud Across Multiple Companies

Fraud rings don’t stop at just one lender. Catching repeat fraud early is key to stopping its spread. Jumio’s cross-customer intelligence provides a broader view of a customer’s risk by connecting identity verification data across multiple businesses in real time to catch repeat fraud attempts and synthetic identities before losses occur.

How Jumio Works Across the Lifecycle

Jumio helps BNPL providers turn every application, every return purchase, and every repayment event into a continuous, connected, contextual identity decision. Jumio can catch synthetic and ring fraud that legacy solutions miss, while approving more legitimate borrowers at checkout speed.
Identity Intelligence

Verify

For flagged or high-risk applicants, Jumio steps up with document, ID, and liveness checks, AML screening, and risk signals to confirm trust before approval.
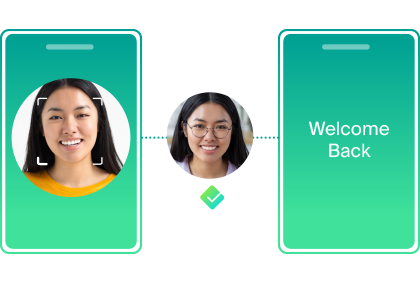
Authenticate

On return purchases or high-value events, Jumio uses selfie-based and device-based authentication to ensure the person behind the transaction is the trusted user.
Analyze

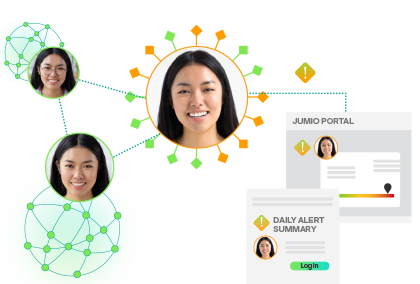
Jumio continuously analyzes risk, surfaces meaningful changes, and enables faster, more confident action across the full customer lifecycle — triggering re-KYC as needed to reassert trust.

FAQs

BNPL fraud refers to fraud schemes that specifically target Buy Now Pay Later lending - most commonly synthetic identities or stolen identities used to pass instant checkout approval, and first-party fraud (bust-out fraud) where a borrower builds a pattern of legitimate purchases before deliberately defaulting.

The most common types of BNPL fraud include synthetic identity fraud, stolen identity fraud, first-party fraud, bust-out fraud and account takeover. Synthetic identities combine real and fabricated personal information to create seemingly legitimate applicants, while bust-out fraud involves building a history of legitimate purchases before deliberately maxing out available credit and then defaulting. Account takeover occurs when a fraudster gains control of an existing account and uses it to make unauthorized purchases.

Identity verification helps BNPL providers establish that an applicant is a real person and that the identity being presented is genuine. ID verification can assess the authenticity of ID documents while biometric checks can confirm the presence of an applicant. Because BNPL approval decisions need to happen in seconds, identity verification needs to operate quickly enough to protect the customer experience while identifying fraudulent applications before approval.

BNPL fraud is not always visible during the initial application. A borrower may initially may legitimate purchases and repayments before their behaviour changes, such as deliberately maxing out available credit in a bust-out scheme. Extended repayment windows can also create opportunities for account takeover after approval. Ongoing analysis can help identify behavioural and identity patterns that indicate emerging fraud risk before losses start.

BNPL lenders require fraud controls that operate at the speed of the customer journey. Manual review of every application adds friction and can slow down the instant approval experience that customers expect. Automated identity verification of high risk transactions can assess document authenticity and confirm an applicant’s presence quickly, while authentication and ongoing analysis can provide additional protection from risk after approval. This allows BNPL providers to apply the appropriate controls throughout the customer lifecycle without slowing down the checkout experience or relying on manual intervention.

See how Jumio protects BNPL lenders across the full customer lifecycle.

Get Started